
How to File a Premises Liability Claim Without a Lawyer
Table of Contents
- Understanding a Premises Liability Claim
- How to Document Evidence for Slip and Fall Accidents
- Building Your Case: Proving Negligence and Liability
- Statute of Limitations for Personal Injury Claims
- Negotiating a Settlement With an Insurance Adjuster
- When to Consider Legal Representation
- Conclusion
- Frequently Asked Questions
Last Updated: September 28, 2026
Understanding a Premises Liability Claim
A premises liability claim is a legal case where someone is injured on another person’s property due to negligence. Property owners have a duty of care to maintain safe conditions and warn visitors of hazards. When they fail to do so and someone is injured, the injured person may have a valid claim for damages. (Source: National Safety Council data)
You can pursue a premises liability claim without a lawyer if you’re organized and thorough. The key is evidence: you must prove the property owner owed you a duty of care, breached it, and caused your injury and damages.
How to Document Evidence for Slip and Fall Accidents
Evidence is everything in a premises liability claim. Start gathering information immediately, act within hours, not days, before property owners clean up or repair hazards. You must prove the hazard existed and the property owner knew or should have known about it.
Evidence to Gather at the Scene
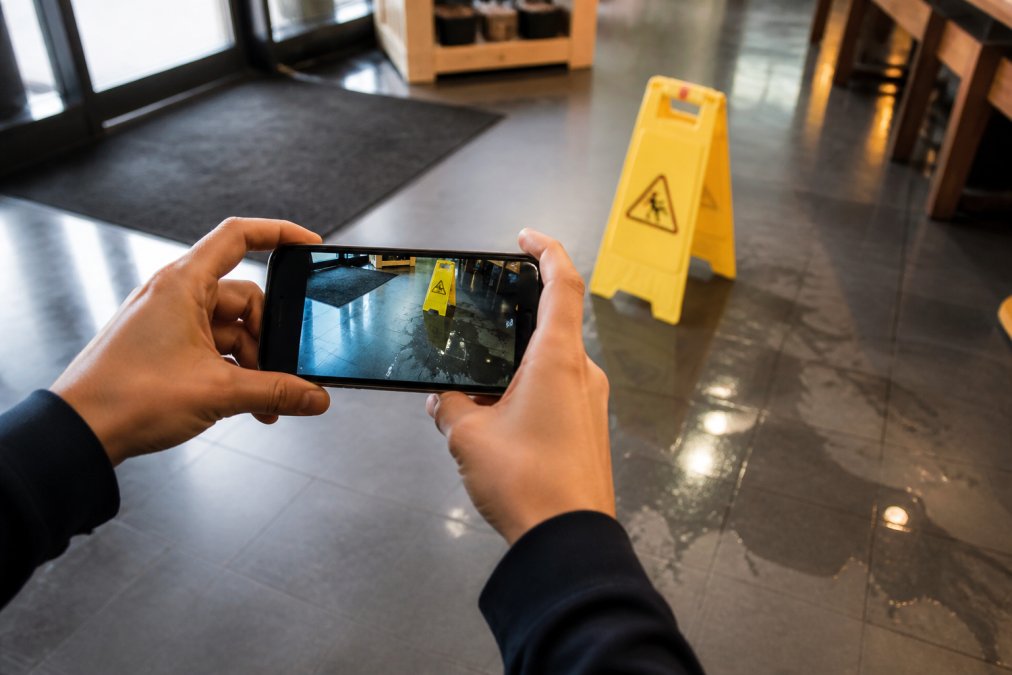
Photograph and video evidence:
- The exact hazard that caused your fall (wet floor, broken step, debris, hole, loose carpet)
- Wide-angle shots of the surrounding area and lighting conditions
- Your visible injuries (bruises, cuts, swelling)
- Any warning signs present, or the absence of warning signs
- Timestamp your photos with date and time metadata or a notepad visible in at least one photo.
Document the scene in writing:
- Date, time (specific: 2:15 PM), and exact location
- Weather conditions if outdoors
- What caused the fall and how long the hazard likely existed
- Foot traffic volume and any maintenance work in progress
Witness information is gold:
- Get full name, phone number, email, and address from anyone who saw the accident
- Record their account of what happened
- Ask if they’ve seen similar hazards before
- Witness statements corroborate your account and are harder for insurers to dismiss.
Report the accident to the property owner or manager immediately:
- Inform them verbally and request an incident report in writing
- Keep the document, it proves the property owner knew about the hazard
- If they refuse, note the date, time, and who refused; this refusal is evidence of negligence
Evidence Preservation Checklist
At the scene (within 1 hour):
- ☐ Photos of the hazard and surrounding area
- ☐ Video walkthrough (30-60 seconds)
- ☐ Photos of your injuries and clothing
- ☐ Written notes: date, time, location, cause of fall
- ☐ Witness names, phone numbers, emails, and statements
- ☐ Property owner/manager name and request for incident report
Within 24 hours:
- ☐ Detailed written account of the accident
- ☐ Follow-up email requesting incident report copy
- ☐ Schedule doctor’s appointment
Within one week:
- ☐ Photograph the hazard again (if it still exists)
- ☐ Note any repairs made by property owner
- ☐ Request surveillance footage in writing
Ongoing:
- ☐ Keep all medical bills, lost wages documentation, and communications
Creating a Personal Accident Report
Write a detailed account within 24 hours while details are fresh. Include: date, time, location, what caused the fall, how you fell, injuries felt, witness names, staff names, photos/videos, statements from property owner or staff, and medical symptoms. Be specific: “I stepped on a wet tile at 2:15 PM and fell onto my right knee and left hand. The floor had no wet floor sign.” Store copies at home, in email, and cloud storage for reference during insurance negotiations.
Building Your Case: Proving Negligence and Liability
To win a premises liability claim, you must prove four elements of negligence.
Establishing the Property Owner’s Duty of Care
Property owners have a legal duty to maintain safe premises by inspecting regularly, repairing hazards promptly, warning of unavoidable dangers, and maintaining adequate lighting. They breach this duty if they knew about a hazard and did nothing, or should have known through reasonable inspection. Document when the hazard likely existed, a hazard that existed for hours shows negligence; one that appeared seconds before your accident is harder to prove. Establishing that a property owner failed to address a known risk often hinges on their adherence to standard protocols for preventing slip hazards on terrazzo floors.
Documenting Your Medical Records and Damages
See a doctor immediately after your accident, even if injuries seem minor. Keep all medical bills, receipts, and records, these document your damages. Calculate lost wages by multiplying your hourly rate by hours missed. Non-economic damages (pain and suffering, emotional distress, reduced quality of life) are harder to quantify but often significant.
Statute of Limitations for Personal Injury Claims
For most premises liability claims, you have a limited time from the date of injury to file a lawsuit. This deadline is strict and may differ in specific situations, such as if the injured person is a minor or if the property owner concealed the injury’s cause. File your claim well before the deadline, insurance negotiations can take time. Timestamp all documents: accident reports, medical visits, and communications with the insurance company.
Negotiating a Settlement With an Insurance Adjuster
Most premises liability claims settle without going to court through negotiation with an insurance adjuster. Adjusters work for the insurance company, not for you. Their job is to close claims as cheaply as possible using rapport-building, leading questions, and psychological pressure. Recognize these tactics and stay disciplined.
How Insurance Adjusters Devalue Pro-Se Claims
Adjusters employ several predictable tactics when dealing with unrepresented claimants. Knowing these tactics in advance helps you avoid the traps.
The “friendly expert” approach: Adjusters begin warmly, saying “I want to help” or “I’ve handled thousands of claims.” This builds false trust to make you comfortable accepting their low valuation. Remember: their expertise is in minimizing payouts, not protecting your interests.
Anchoring with a low initial offer: Insurance companies open with offers 30-50% below reasonable settlement value. This “anchor” becomes your negotiation baseline. Most people accept something closer to the opening offer than their actual demand. Don’t let the first number frame the entire negotiation.
Questioning the severity of your injuries: Adjusters may suggest injuries are minor because you saw a doctor only twice or didn’t need surgery. This is a pressure tactic. Stand firm on what your doctors documented and what you experienced. (Source: U.S. Consumer Product Safety Commission (CPSC) guidelines)
Highlighting gaps in your evidence: Adjusters will exaggerate the significance of missing photos or witness statements to justify lower offers.
Preparing Your Demand Letter
A demand letter is your formal settlement proposal. Include: a chronological description of the accident, proof of negligence, documentation of injuries and medical treatment, a detailed list of damages with dollar amounts, the total amount requested, a 30-day response deadline, and a statement that you’re open to negotiation. Be specific about damages: “I was unable to work for six weeks, losing $8,400 in wages.
Calculating a Reasonable Demand Amount
Economic damages include medical bills, lost wages, future medical costs, and transportation. Add these for your baseline. Non-economic damages (pain and suffering) use the multiplier method: multiply economic damages by 2-5 depending on severity (2× for minor injuries, 3-4× for moderate, 5-7× for severe). Example: $15,000 economic damages × 3.5 = $52,500 demand. Adjust based on recovery length, permanence of injuries, impact on daily life, and strength of negligence evidence.
What Not to Say to an Insurance Adjuster
Adjusters will try to get you to say things that weaken your claim. Be careful with your words.
When Negotiation Stalls
If the adjuster refuses to budge, request a supervisor review, send a follow-up demand letter with additional evidence, file a complaint with your state’s Department of Insurance, or consult an attorney. You are not obligated to settle. The threat of litigation often moves adjusters from lowball offers to reasonable ones.
When to Consider Legal Representation
Consider hiring a lawyer if your injuries are severe, the insurance company denies liability, multiple parties are involved, the property owner disputes facts, you’re offered far less than your damages, or the claim involves complex negligence issues. Most personal injury lawyers work on contingency, you pay nothing upfront; they take a percentage of your settlement. At Abkarian Law Group, we’ve handled premises liability claims over 34 years.
Conclusion
Filing a premises liability claim without a lawyer is possible when you’re organized and thorough. Document evidence immediately. Gather medical records. Calculate all damages. Prepare a strong demand letter. Understand the statute of limitations. Communicate carefully with the insurance adjuster.
Frequently Asked Questions
What are the key elements of a premises liability claim?
A premises liability claim requires proving four elements: the property owner owed you a duty of care, they breached that duty through negligence or failure to maintain the property, you suffered injury as a direct result, and you incurred measurable damages (medical bills, lost wages, pain and suffering). Without evidence supporting all four, your claim will likely fail. This is why thorough documentation of the hazard, your injury, and the property owner’s negligence is critical to success.
What is the statute of limitations for a personal injury claim in California?
In California, you generally have two years from the date of injury to file a lawsuit for personal injury claims, including premises liability. However, the discovery rule may extend this deadline if you did not immediately discover your injury. Acting quickly to preserve evidence and document your claim is essential, as waiting too long can result in losing your legal right to pursue compensation entirely.
What should I avoid saying to an insurance adjuster?
Never admit fault, downplay your injuries, or agree to a settlement before you have fully documented your damages. Avoid casual statements like ‘I’m fine’ or ‘it wasn’t a big deal’, adjusters use these against you. Do not discuss your medical history beyond what relates to the accident. Keep conversations brief, stick to facts, and do not speculate about how the accident happened. Always send written communication rather than speaking by phone when possible, so you have a record.
When should I hire a lawyer instead of handling my claim alone?
Consider legal representation if the property owner disputes liability, your injuries are severe, you face comparative negligence claims, or the insurance company denies your claim outright. Insurance bad faith tactics, like unreasonably delaying payment or offering far below fair value, are also red flags. An attorney can shift the burden of proof onto the property owner and handle litigation if settlement negotiations fail.